
To sell an online business in 2026, get a data-backed valuation, prepare 12 to 24 months of clean financials, choose the sale route that fits your price band, run a confidential process that puts qualified buyers in competition, negotiate the letter of intent, then complete due diligence, contracts, escrow and handover.
I have spent the past 16 years buying, selling and advising on technology businesses, and the question I still hear most often is the plainest one: how do I actually sell this thing? Founders who can build a product, grow a brand or scale an agency often find the exit is the one part of the journey nobody taught them. This guide is my attempt to fix that.
Since 2010, FE International has completed more than 1,500 transactions across SaaS, ecommerce, agencies, AI, cybersecurity, edtech and fintech, with a 94.1% success rate on the businesses we take to market. That gives us a large sample of what works, what buyers pay for and where deals go wrong. Everything below comes from that sample, backed by the most current market data available.
The backdrop matters too. Global deal value climbed 41% year on year to $2.4 trillion in the first five months of 2026, which puts the year on course for the second-highest total on record. Buyers have capital and a reason to deploy it. What has changed is that they are choosier, and that rewards founders who prepare.
One note on scope before we start. This article is about selling a business that operates online: a SaaS product, an ecommerce brand, an agency, an app, a content site, a fintech or edtech company. If you searched for how to start selling products online, that is a different subject and you will find better guides elsewhere. If you own a digital business and want to know when to sell it, what it is worth, who will buy it and how the process runs, read on.
Is 2026 a Good Year to Sell an Online Business?
Short answer: yes, and for reasons that have more to do with buyers than with sellers.
Three data points frame the year. Global M&A rose 40% to $4.9 trillion in 2025, the second-highest annual total ever recorded, and the first five months of 2026 kept climbing, putting the market on pace to top $5.3 trillion, just below the 2020 record of $5.6 trillion. Second, in a survey of 1,500 corporate executives and private equity dealmakers, more than 80% expect both deal volume and deal value to increase over the next 12 months. Third, technology is expected to keep attracting the highest deal values of any sector in 2026, supported by investment in AI, data and digital infrastructure.
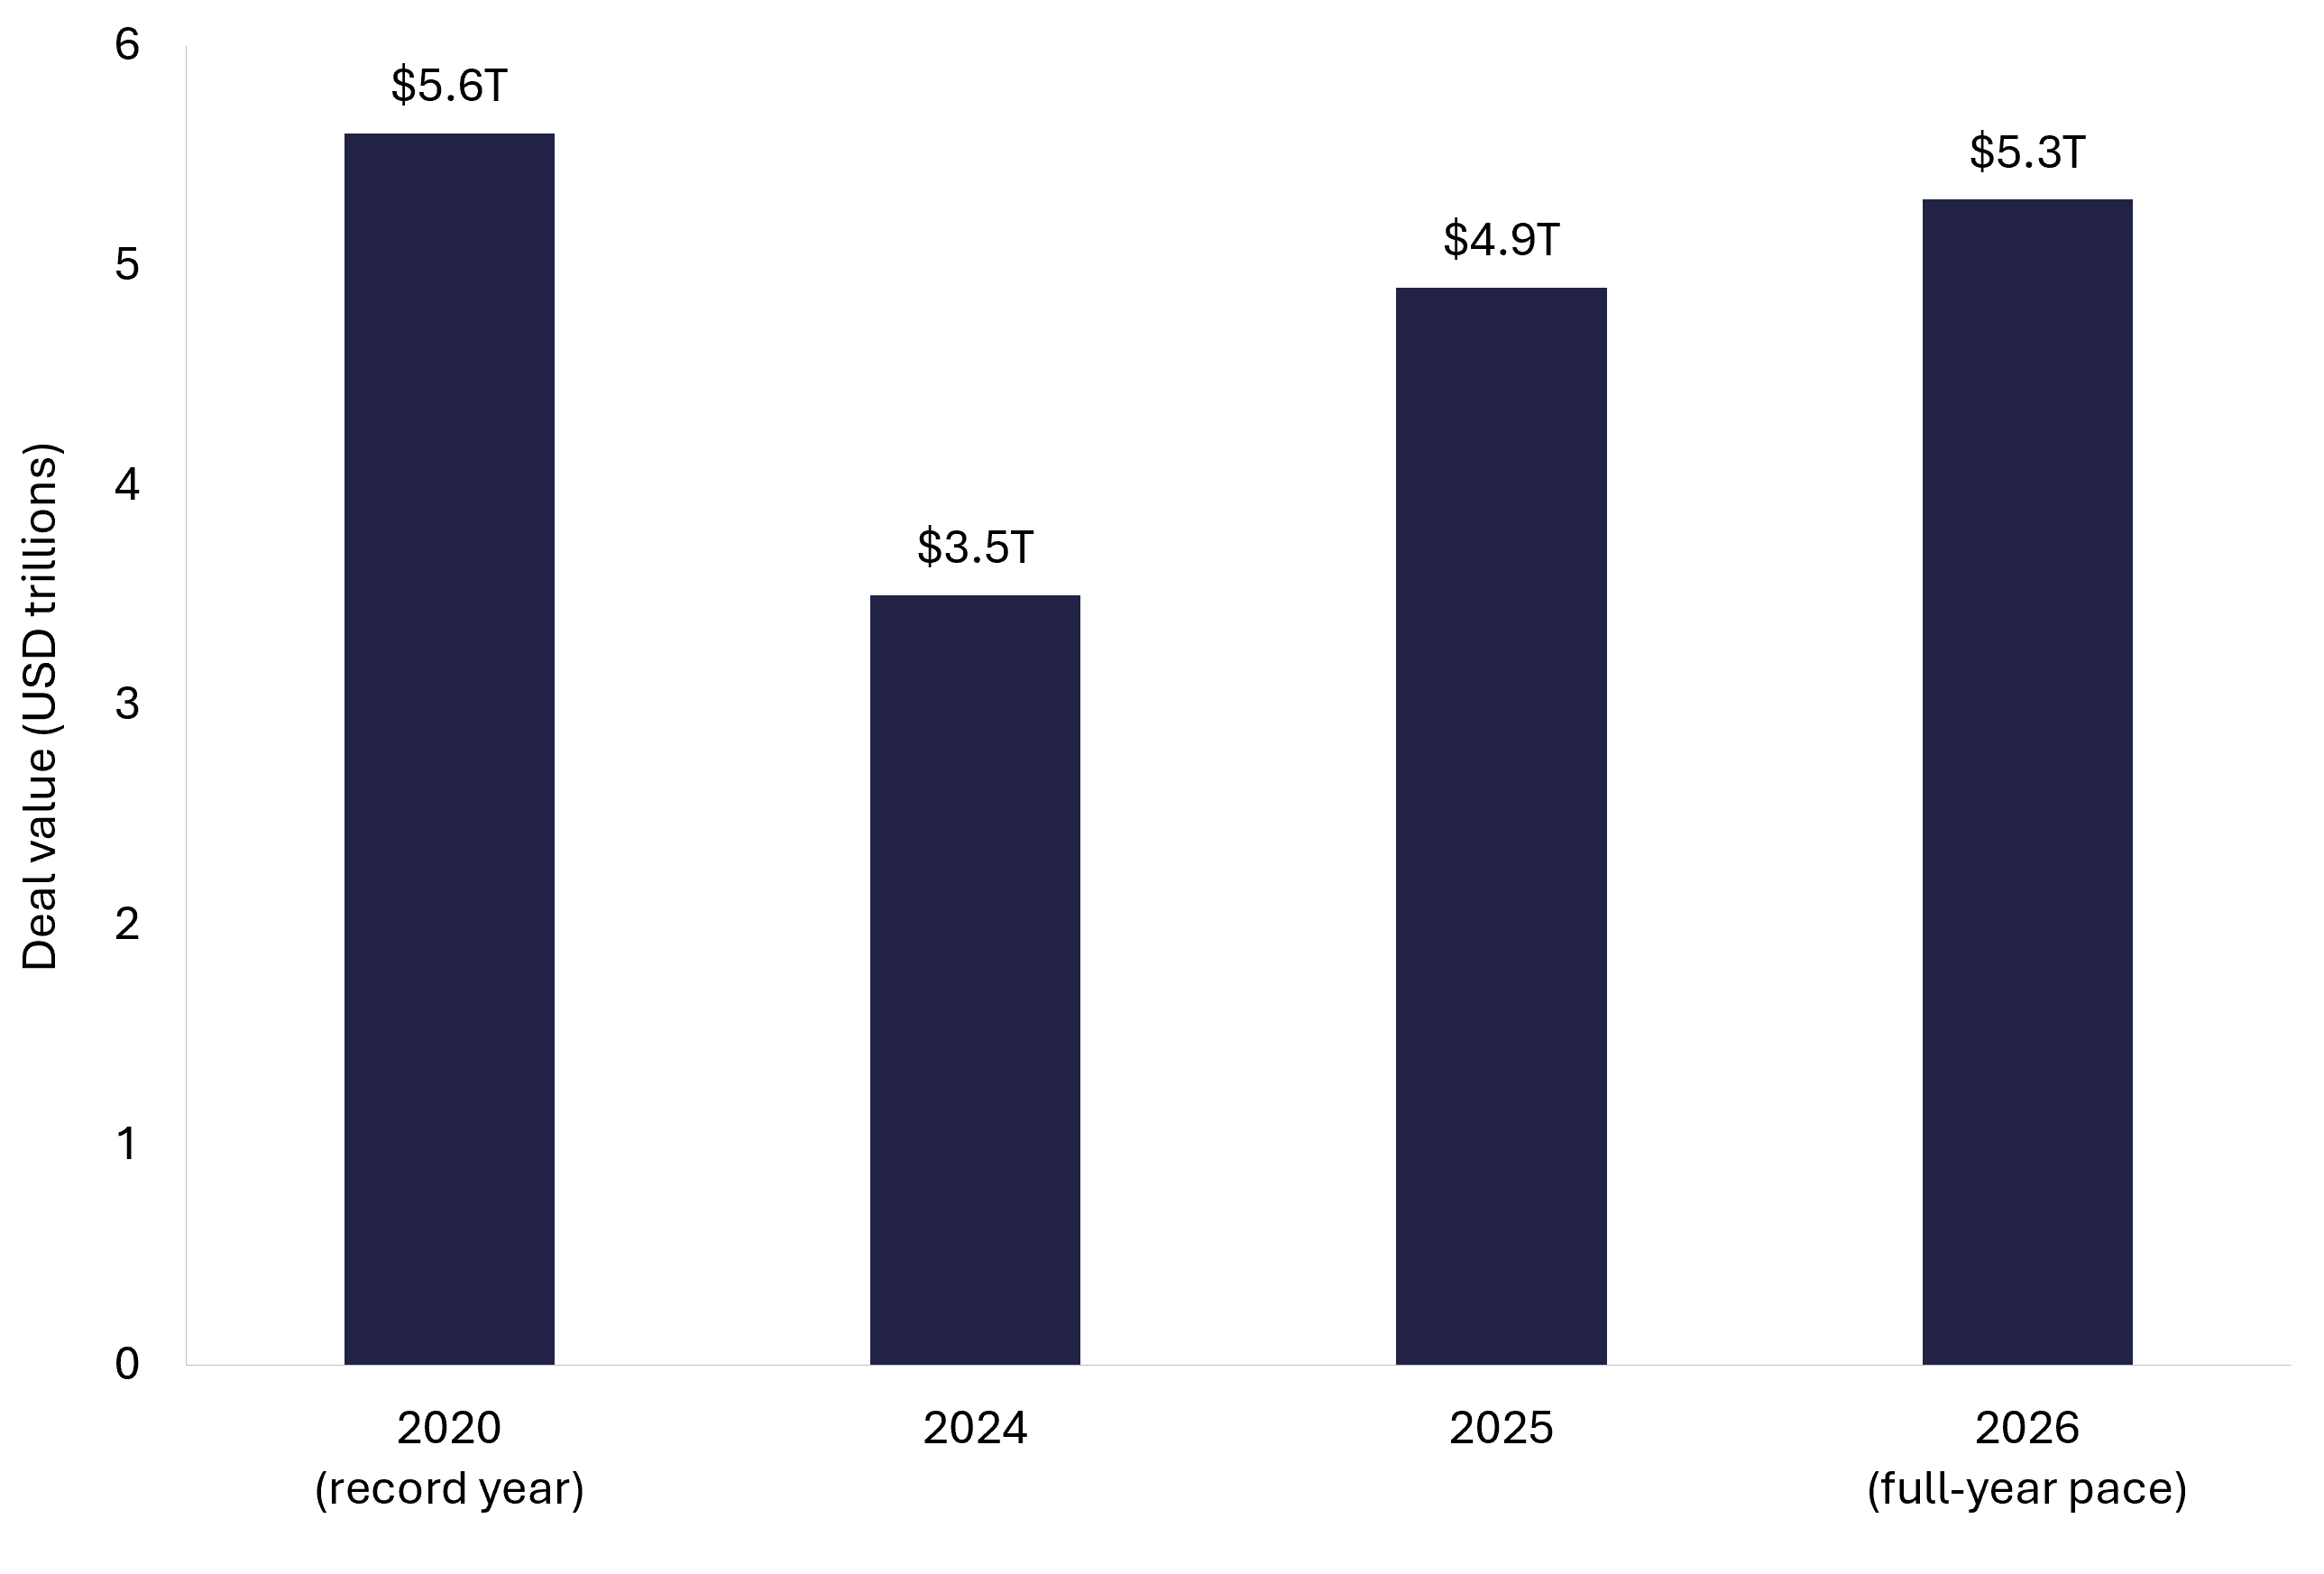
What I find more useful than the headline totals is what sits underneath them. Global M&A totaled an estimated $1.3 trillion in the second quarter of 2026, up 35.3% year on year, while deal count held steady and the median enterprise value to EBITDA multiple stayed at 10.2x on a trailing twelve-month basis. Steady volume and disciplined multiples are exactly what a seller wants. They mean the benchmarks are clear, buyers know what a fair price looks like, and a business that beats the benchmark on retention, margin or growth stands out quickly.
The same data shows strategic acquirers taking a larger share of activity, with corporate-led M&A holding above $890 billion in the quarter. Corporate buyers fund deals from balance sheets and stock rather than borrowed money, so they are less sensitive to interest rates, and they buy capability: a product that plugs a gap, a customer base they can cross-sell, a channel they do not have. If your online business has any of those, 2026 is a year when someone is looking for it.
Vertical texture matters here, because "online business" covers a lot of ground. Subscription software with high net revenue retention is being priced on growth durability. Ecommerce brands that own their customer relationship (email lists, repeat purchase rates, direct traffic) are attracting buyers who have learned to discount channel-dependent stores. Agencies with retainer-heavy revenue and a second layer of management are trading at a premium to project-based shops. Cybersecurity, fintech and edtech companies are benefiting from compliance-driven and reskilling-driven demand that does not switch off when the wider economy slows.
The money did not leave the market in 2026. It became selective, and selective buyers pay for preparation.
When Should You Sell Your Online Business?
The best time to sell is when you still have growth left to hand over. I know that is not what most founders want to hear, because the instinct is to squeeze out one more year and sell at the top. In practice, buyers pay for the future, not the past, and a business whose trailing twelve months show steady, explainable growth will command a better multiple than one that has plateaued, even if the plateau is at a higher revenue figure.
A few signals tell me a founder is approaching the right window:
- Growth is compounding, but the founder can see the ceiling of what they personally can do. The next stage needs capital, a sales team, or an operator with different skills.
- The business runs without the founder for weeks at a time, or could with modest work.
- No single customer, channel, supplier or platform accounts for a dangerous share of revenue.
- The founder has a personal reason to move on: a new venture, a family change, or simple fatigue after five or ten years in the same seat.
- Trailing twelve-month numbers are clean, and the next twelve are predictable.
Market timing matters less than business timing, and the demand backdrop in 2026 is a good example of why. Worldwide IT spending is forecast to reach $6.37 trillion this year, up 14.2%, with software the fastest-growing large category at 15.5%. Buyers of software, digital services and online brands are underwriting growth they can see in their customers' budgets. Waiting for a better market is rarely the right reason to delay. Waiting until the business is ready usually is.

Vertical timing also matters. An ecommerce brand is usually best marketed shortly after its peak season, so the trailing twelve months include the strong quarter and the buyer inherits inventory planned for the next one. A SaaS business should let a pricing change or a new plan structure settle for at least two quarters so retention data reflects it. An agency is easier to sell after major client contracts renew rather than before. Edtech companies tied to academic or enrollment cycles should plan the process around them, so the buyer sees a full cohort of data.
Then there is tax timing, which founders often discover too late. Founders of US C corporations who hold qualified small business stock should check the holding period rules under Section 1202 of the Internal Revenue Code. For stock issued after July 4, 2025, the exclusion now steps up over time: 50% of eligible gain after three years, 75% after four, and 100% after five, with a per-issuer cap of $15 million (up from $10 million) and a gross-asset ceiling of $75 million (up from $50 million). Stock issued on or before that date keeps the older five-year, $10 million rules. I am not a tax adviser, and this varies by country and by structure, but the point stands: know your dates before you set your timeline.
There are also times not to sell, or at least not yet. If you have just lost a top client, are midway through a platform migration, or your books need three months of clean-up, fix those first. A buyer will find every one of those issues in diligence and price them in. Better to spend a quarter preparing than to accept a discount that lasts forever.
Buyers pay for the future. Sell while the next chapter is still visible and still yours to describe.
How Much Is Your Online Business Worth in 2026?
Every valuation starts with the same question: which earnings figure are we multiplying? Get this wrong and everything downstream is wrong.
Three methods cover almost every online business:
- Seller's discretionary earnings (SDE) is the profit available to a single owner-operator after adding back the owner's salary, benefits and discretionary expenses. It fits owner-run businesses, typically those valued under roughly $5 million, where a buyer will step into the founder's seat.
- Adjusted EBITDA is earnings before interest, taxes, depreciation and amortization, normalised for one-off items, with a market-rate management cost left in. It fits businesses with a team that will keep running the company after the founder leaves.
- Revenue or ARR multiples apply to fast-growing subscription businesses where buyers are paying for the trajectory rather than today's profit.
The most common error I see is a founder applying an EBITDA multiple they read about to their SDE figure. A business with $600,000 of SDE where the founder draws a $150,000 salary has about $450,000 of EBITDA. Same business, same cash, two numbers a third apart. Our guide on how to value a website or internet business walks through the arithmetic with examples.
Benchmarks then set the range. Across all global M&A, the median enterprise value to EBITDA multiple held at 10.2x on a trailing twelve-month basis through the second quarter of 2026, with healthcare at 12.6x and energy at 8x. Those medians are skewed toward large deals. Owner-operated online businesses under $5 million typically trade at lower multiples of SDE, while private subscription software trades on ARR in a range that widens with scale and retention. Our 2026 SaaS valuation multiples guide has the private deal bands we see in our own work.

What moves a business within its range is risk. Buyers price risk, and every item you remove from their list shows up in your multiple. The list is different for each vertical:
- SaaS: net revenue retention, gross churn, gross margin, growth rate against the Rule of 40, customer concentration, and how much of ARR sits on annual contracts.
- Ecommerce: gross margin after fulfilment and returns, repeat purchase rate, share of revenue from owned channels, inventory turns, supplier terms, and whether the sales channel accounts transfer to a buyer. Our guide to valuing an ecommerce business covers this in depth.
- Agencies: retainer versus project revenue, client concentration, EBITDA margin, and whether client relationships sit with the founder or with account leads. See how we approach agency business valuation.
- Edtech: cohort retention, lifetime value per learner, and the mix of institutional versus consumer revenue.
- Fintech: transaction volume, take rate, licensing and compliance posture, and payment processing margin.
- Cybersecurity: ARR quality, certifications, renewal rates and the depth of the engineering team.
- AI: proprietary data, defensibility against foundation models, and the true cost of compute inside gross margin.
Two things are consistent across all of them: clean, consistent financials and low dependence on the founder. A buyer who can rebuild your numbers from raw exports and see that the business runs without you will pay for that certainty. A free, confidential valuation from FE International draws on comparable transactions from our own deal history, which is the fastest way to find out where your business really sits.
Buyers price risk. Every item you remove from their risk list shows up in your multiple.
Which Sale Path Fits Your Price Band?
Price band changes everything about how a sale should run: who the buyers are, how deep diligence goes, what documents are needed, and how much process the business can justify.
At FE International we run complementary routes. Businesses valued under $1 million move through our M&A Platform, a self-serve route where the seller's verified financials and metrics go in front of our screened buyer network, with standardised documents and FE International's screening in place, without the full advisory process. Businesses valued above $1 million work with a dedicated advisory team that runs a confidential, competitive process end to end, with in-house financial and legal support from valuation to closing. Larger transactions move into our investment banking practice. The routes are designed to fit the deal, and the starting point for all of them is the same: a free valuation that tells you which band you are in.
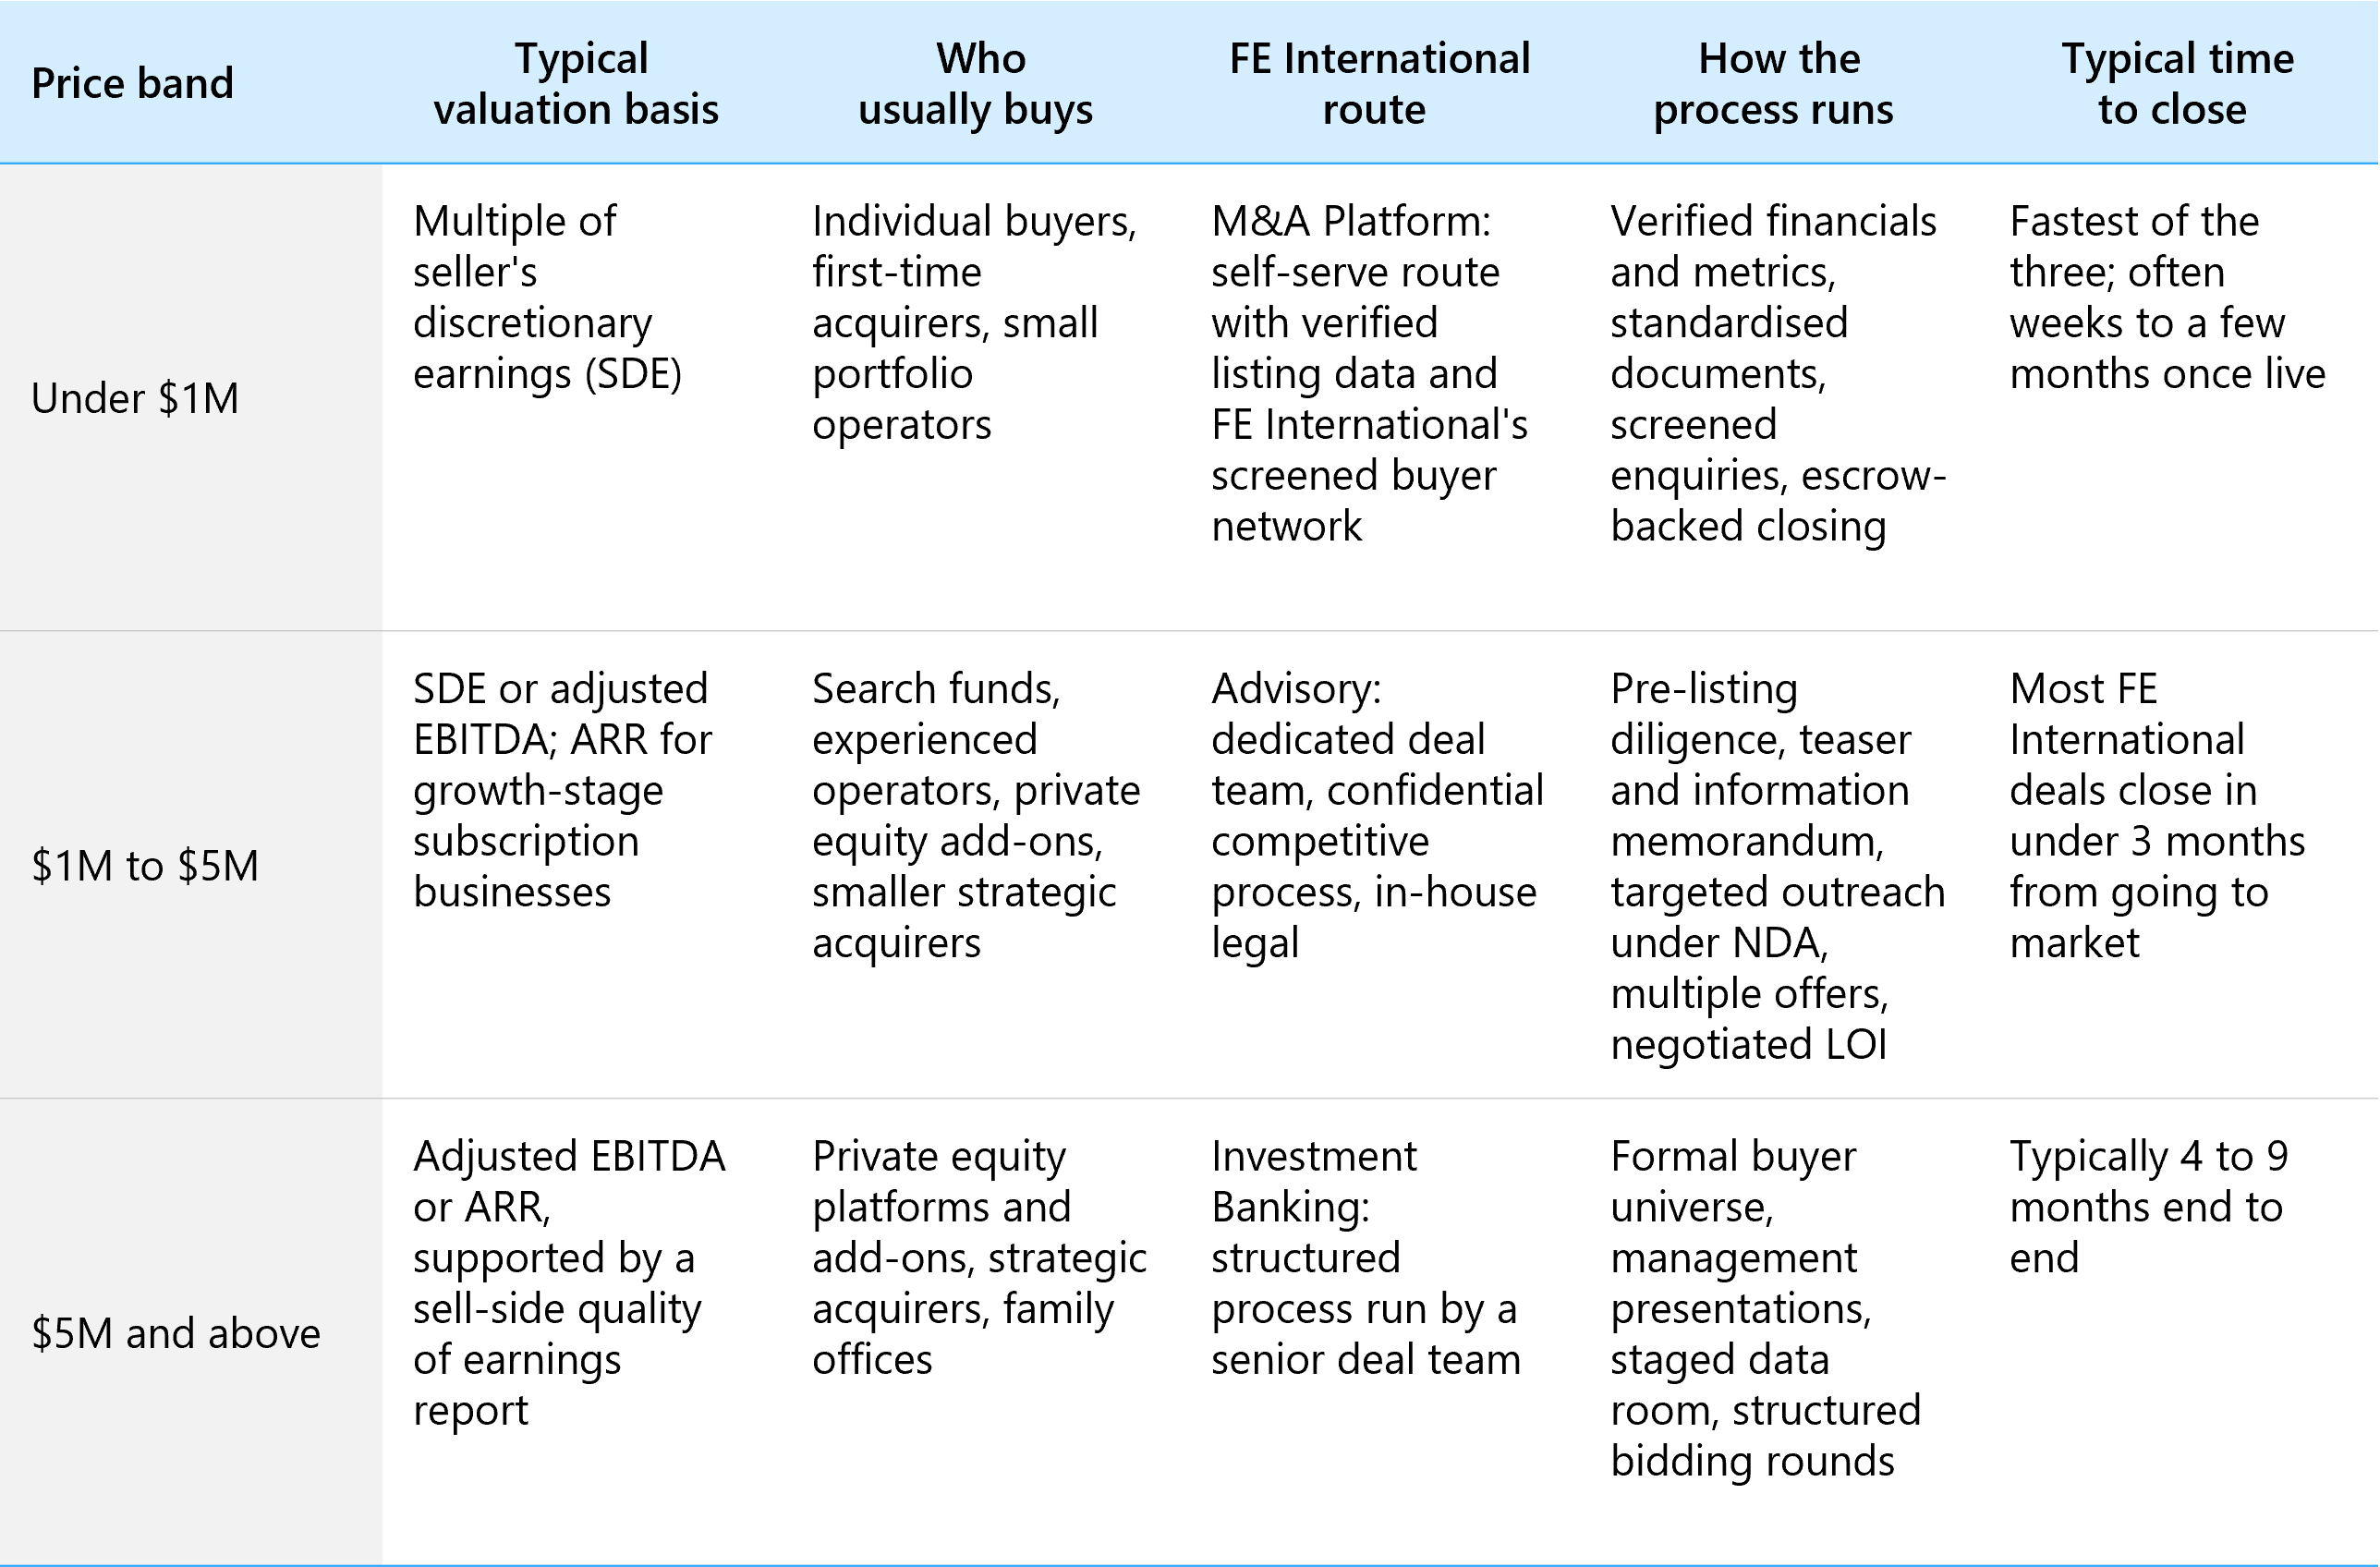
Two notes on reading the table. First, the bands are guides, not walls. A $900,000 SaaS business with 40% growth and enterprise customers may justify a full advisory process; a $1.5 million content site with simple operations may not need the depth of a banking process. Second, the buyers change at each threshold. Under $1 million, most buyers are individuals or small operators paying largely in cash. Between $1 million and $5 million, search funds, experienced operators and add-on buyers appear. Above $5 million, private equity platforms and strategic acquirers dominate, and they run diligence with teams of specialists. Matching the process to the buyer pool is where an advisor earns their fee.
The right process is the one your buyer pool expects. Under-process a large business and you leave money on the table; over-process a small one and you burn time.
Who Buys Online Businesses in 2026, and What Does Each Buyer Pay For?
Different buyers price the same business differently, and a well-run process exists to find the one who values it most. Here is who is active in 2026.
Individual buyers and first-time acquirers. This is the largest group by count, and the dominant buyer below $1 million. They are often professionals leaving corporate roles, operators who already run one small business, or founders who sold and want to buy back in. They pay for simplicity: documented processes, transferable accounts, and a business that produces predictable cash from month one. Financing is usually a mix of savings, seller financing and, in the US, SBA-backed lending, so the cleanliness of your financials directly affects what they can borrow.
Search funds and entrepreneurs through acquisition. This buyer group has grown into a real force. Stanford Graduate School of Business has tracked more than 850 core search funds in the United States and Canada, with a 58% aggregate acquisition rate, roughly 20 months from launch to purchase, and a median purchase price of $16 million for acquisitions in 2024 and 2025. The top industries they targeted were services, software and education, which maps almost exactly onto agencies, SaaS and edtech. Search fund buyers pay for durable cash flow with a growth plan attached, and they tend to be thoughtful, well-advised counterparties who move at a steady pace.
Private equity and PE-backed platforms. Buyout funds are sitting on $1.3 trillion of dry powder, and in 2025 global buyout-backed exit value jumped 47% to $717 billion, with sales to corporate buyers up 66%. What matters for founders is how PE underwrites a deal today. The rule of thumb in that report is that "12 is the new 5": a typical deal now needs 10% to 12% annual EBITDA growth to hit the returns that 5% growth once delivered. PE platforms therefore pay premiums for businesses that add margin, cross-sell potential or a new capability to an existing portfolio company. For online businesses between roughly $2 million and $50 million, the add-on acquisition is the most common way to meet private equity.

Strategic acquirers. Corporates buying capability, customers or distribution. Corporate-led M&A held above $890 billion in the second quarter of 2026 as strategics took share from leveraged buyers. A strategic can pay the highest price because the business is worth more inside their platform than on its own. The catch, which I have watched play out many times, is that a strategic approached cold rarely closes on the terms first discussed. I have a friend whose website drew three strategic offers over several years: one all in stock that halved during diligence, one that never progressed, and one that switched from cash to stock at the final step. The lesson is not to avoid strategics. It is to bring them into a competitive process where the timeline and the alternatives are yours.
Family offices and independent sponsors. Smaller in number but often flexible on structure and patient on timeline. They frequently want the founder to stay involved with equity, which suits some sellers and not others. Our guide comparing private equity, strategic and individual buyers goes deeper on how each group runs diligence.
The practical takeaway: do not decide in advance which type of buyer is "right." Prepare the business so that all of them can underwrite it, then let the process reveal who values it most.
Different buyers price the same business differently. A process exists to find the one who values it most.
How Do You Prepare an Online Business for Sale?
Preparation is where value is created or lost, and most of it happens before anyone knows the business is for sale. I would start 12 to 24 months out if you can, and here is the order I would work in.
Clean the financials first. Separate personal and business expenses, adopt consistent accounting (accrual for anything with deferred revenue or inventory), reconcile every account monthly, and make sure the numbers in your bank, your accounting software and your payment processor agree. Buyers in 2026 rebuild your figures from raw exports rather than trusting a spreadsheet. In a 2025 survey of 1,000 corporate and private equity leaders, 86% already use generative AI in their M&A work, and 88% of private equity executives have invested at least $1 million in building that capability. Practically, that means an analyst can upload three years of transaction data and have every anomaly flagged in an afternoon. Your numbers need to survive a machine reading them.
For businesses above roughly $1 million, commission a sell-side quality of earnings report. It normalises earnings, tests revenue recognition and finds the issues before the buyer does. Our guide on quality of earnings in tech M&A explains what a QoE covers and why it shortens diligence.
Reduce owner dependence. Document processes, delegate customer-facing relationships to team members, and put a second signature on supplier and platform accounts. If you are the only person who can deploy code, close a client or approve a purchase order, buyers will price that risk or ask you to stay longer than you want to.
Fix concentration where you can. A top customer above 20% to 25% of revenue, a single acquisition channel above half of new customers, or one supplier behind most of your margin are the three concentrations buyers flag most often. You may not be able to remove them in a year, but showing a trend in the right direction matters.
Get the legal house in order. Confirm you own the IP (contractor agreements with assignment clauses), that key contracts are assignable, that your privacy and data handling match the jurisdictions you sell into, and that the entity structure is clean. Check that every platform account you rely on can transfer to a new owner, which is a frequent surprise for ecommerce and app businesses.
Then the vertical specifics:
- SaaS and cybersecurity: consistent churn definitions across the whole history, cohort tables built from raw data, a security and compliance summary (SOC 2 or equivalent where relevant), and a documented codebase.
- Ecommerce: inventory schedule with ageing, landed cost by SKU, returns data, supplier agreements, and evidence of owned-channel strength such as the share of revenue from email and direct traffic.
- Agencies: contract schedule showing retainer versus project revenue, utilisation and margin by client, and named account leads for each relationship.
- Edtech and fintech: enrollment or transaction cohorts, regulatory and licensing status, and any accreditation or partner agreements the business depends on.
- Content and affiliate sites: traffic source diversity, revenue by partner, and a record of how the site has performed through search updates.
One more thing founders underrate: keep growing during the process. A business that softens while it is on the market invites a price renegotiation. Plan the sale so that you can still run the business well while it happens, which is another argument for having someone else handle buyer traffic.
Diligence in 2026 is run by software as much as by people. Prepare numbers that survive both.
What Does the Sale Process Look Like, Step by Step?
Here is the sequence we run at FE International, which is also a fair template for any well-run sale.
- Valuation and goals. A confidential conversation about the business, the numbers and what you want from the exit: price, timing, what happens to the team, how long you are willing to stay. We provide a valuation based on comparable transactions and tell you which route fits. This stage is free and carries no obligation.
- Pre-listing diligence and engagement. We review financials, contracts, traffic and operations before the business goes anywhere near a buyer. We turn down more than 90% of the businesses that approach us, which is one reason 94.1% of those we take to market close. This step also produces the data room, so buyers get answers rather than delays.
- Teaser and information memorandum. An anonymised teaser that describes the opportunity without identifying it, and a detailed memorandum with financials, metrics, operations and growth levers, released only after a signed NDA.
- Confidential marketing to qualified buyers. The teaser goes to our buyer network and to targeted strategic and financial acquirers we identify for the specific business. Buyers are screened for capital and intent before they see anything sensitive, and direct competitors sit on a hold list unless you decide otherwise. The average business sold through FE International receives over 200 qualified enquiries.
- Buyer meetings and management presentations. Video calls between you and shortlisted buyers, with your advisor managing questions and follow-up so you are not answering the same question thirty times.
- Offers and the letter of intent. Offers are compared on structure and certainty, not just price. The chosen buyer signs an LOI that sets price, structure, exclusivity period and timeline. This is the point where leverage shifts toward the buyer, so the terms in the LOI matter a great deal (more on that below).
- Due diligence. Financial, legal, technical and commercial. Typically four to eight weeks for a well-prepared business. The pre-listing work pays off here, because most of the requests have already been answered.
- Purchase agreement. The asset or stock purchase agreement, with representations, warranties, indemnities, non-compete and transition terms. Our in-house legal team drafts and negotiates these documents as part of the engagement, which removes a layer of cost and coordination for the seller. If you are selling without an advisor, budget for an experienced M&A attorney here.
- Escrow and closing. Funds go into a third-party escrow, assets and accounts transfer, and funds release when both sides confirm. Our guide to the escrow process covers how this protects both parties.
- Transition. Usually 30 to 90 days of training and handover, sometimes longer for complex businesses, occasionally structured as a paid consulting agreement.
On timing: most deals at FE International close in under three months from going to market, though the full journey from first conversation to funds received is usually four to six months once preparation is included, and larger or more complex transactions can run six to nine months. What shortens the timeline is not urgency. It is preparation and a buyer pool that arrives ready to transact. Our guide on how to choose an M&A advisor lists the questions to ask any firm about its process before you sign.
A good process is boring on purpose. Surprises are what cost you money.
How Do You Sell Your Business Online Without a Public Listing?
"Sell my business online" is one of the most searched phrases in this space, and it usually means one of two things. Either a founder wants to sell a business that operates online, or the owner of any business wants to use online channels to find a buyer. Both are sensible, and both run into the same trap: the assumption that selling online means listing publicly.
Public listings have a place, mainly for very small assets, but the trade-offs are real. Competitors, staff, suppliers and customers can work out that your business is for sale. Enquiries are mostly unqualified. In our own experience over the years, the average listing on general business-for-sale sites draws around 18 enquiries, and a good share of those are tyre-kickers, duplicates or buyers without funds. Compare that with the 200-plus qualified enquiries the average business sold through our process receives, and the difference is not marketing spend. It is the compounding effect of a buyer network built over 1,500 transactions and a screening process that puts capital and intent ahead of curiosity.
A confidential online sale in 2026 works like this. An anonymised teaser describes the business by model, size, growth and vertical without naming it. Buyers who match the profile sign an NDA and are screened. Only then do they see the memorandum and, later, a virtual data room with staged access to sensitive material such as customer names and contracts. Management meetings run over video across time zones. Offers, the LOI and the purchase agreement are negotiated electronically, funds move through escrow, and accounts and assets transfer remotely. The entire transaction can complete without the buyer and seller ever being in the same room, and without anyone outside the process knowing it happened until the announcement you choose to make.
That is what selling a business online should mean: reaching more qualified buyers across more geographies, faster, with less exposure. For businesses under $1 million, our M&A Platform delivers a lighter version of the same discipline, with verified financials and screened buyers. For businesses above $1 million, the full advisory process does the work. Either way, the first step is the same: request a free valuation and we will tell you which route fits and what to expect.
Selling online should mean reaching more qualified buyers, not telling the whole internet your business is for sale.
Should You Sell Your Online Business Yourself or Use an M&A Advisor?
I get asked this constantly, and the answer is not always "use an advisor." Here is how I would think it through.
Selling yourself makes sense when the asset is very small, the buyer is already known (a competitor you trust, a team member, a partner), the business is simple to explain, and you have the time and temperament to run a negotiation while also running the company. Plenty of founders have done it successfully. It is worth knowing what "doing it yourself" includes, though: valuing the business correctly, preparing the financial package, marketing it without exposing it, screening buyers for funds, negotiating an LOI, managing diligence requests for weeks, hiring and briefing an attorney to draft and negotiate the purchase agreement, arranging escrow and handling the transfer. Each of those is a place where a first-timer can lose value, and the most expensive losses tend to happen late, when a single buyer knows you have no alternative.
Working with an advisor makes sense when the business is worth $1 million or more, when confidentiality matters, when you want competitive tension between buyers, or when you cannot afford to take your eye off the business for six months. An advisor's fee is real and you should understand it before you sign. Weigh it against three things: the price uplift from competition and positioning, the certainty of closing, and the value of your own time and focus during the process.
Two more points that are often missed. First, if you already have a buyer, you can still engage an advisor. Most firms, ours included, will carve out prospects you have already spoken to at a reduced fee, so you keep the relationship and gain the process. Second, the reverse also happens: a number of our clients tried selling themselves first, spent six to twelve months on it, then retained us. There is no shame in that, but it is time and momentum you do not get back.

The question I would encourage every founder to ask is not "which route has no fee?" but "which route puts more money in my account after fees, taxes and risk?" For a small, simple asset with a buyer in hand, the honest answer might be selling it yourself. For most online businesses above $1 million, the honest answer is a competitive process run by people who do this every week.
Ask which route puts more in your account after fees, taxes and risk, not which route has no fee.
What Deal Terms Matter Beyond the Headline Price?
Headline price is a number. Structure is what you receive. The letter of intent is where structure gets set, and it deserves as much attention as the valuation.
Exclusivity. Buyers will ask for a period, often 30 to 90 days, during which you cannot talk to anyone else. Keep it as short as the diligence plan allows and tie extensions to milestones, because exclusivity is the moment your alternatives disappear.
Cash at close versus deferred consideration. Earnouts pay part of the price later based on performance. They can bridge a valuation gap, and they can also become a source of dispute if the metrics depend on decisions the buyer controls after closing. If you accept one, tie it to revenue or gross profit rather than net income, define the measurement precisely, and limit the buyer's ability to change the business in ways that affect it. Seller notes, holdbacks and escrows for representations and warranties, and equity rollovers into the buyer's company all shift risk and reward between the parties. None of them is inherently bad. Each should be priced.
Working capital. Most agreements set a target level of working capital the business must have at closing, with a price adjustment either way. For ecommerce businesses with inventory and for agencies with receivables, this number can move the proceeds materially, so agree the definition early.
Asset sale versus stock sale. Buyers usually prefer to buy assets, because they get a stepped-up tax basis and leave liabilities behind. Sellers, particularly founders of C corporations who may qualify for the Section 1202 exclusion described earlier, often prefer a stock sale. The difference can be worth more than a full turn of multiple, which is why tax advice belongs at the start of the process, not after the LOI.
Transition and non-compete. Expect a 30 to 90 day handover at minimum, sometimes a paid consulting period, and a non-compete that covers the business's specific market for a defined number of years. Be clear about what you plan to do next before you sign, so the restriction does not block it.
Representations and warranties. These are the promises you make about the business, backed by indemnities. Disclose thoroughly, because a disclosed issue is priced while an undisclosed one is litigated. Representation and warranty insurance is increasingly available on mid-market deals and can replace part of the escrow.
The positive way to see all of this: structure is what lets a buyer pay more. A buyer who can defer a portion, roll the founder into equity or protect themselves on working capital can often stretch on headline price. Your job, with your advisor, is to make sure you understand exactly what each element is worth and what it costs you.
Headline price is a number. Structure is what you actually receive.
Which Mistakes Cost Founders the Most When Selling?
After a few hundred conversations with founders who tried, succeeded or stalled, the same handful of mistakes come up.
- Pricing off public or headline multiples. A $700,000 SaaS business is not priced like a public company or a nine-figure platform. Use comparable private transactions in your size band.
- Letting the business soften during the process. Every dip invites a renegotiation. Keep marketing, keep shipping, keep selling.
- Disclosing too early or too widely. Telling the wrong competitor or a key employee before you have a signed buyer creates risk you cannot undo.
- Negotiating alone with one buyer. Leverage comes from alternatives. Without them, the buyer sets the terms.
- Messy or inconsistent data. Changing how you define churn, revenue or cost midway through your history reads as a red flag even when the intent was innocent.
- Leaving tax until after the LOI. Structure decisions are hardest to change once a buyer has anchored on a number.
- Choosing an advisor on fee alone. Ask about buyer network, completed deals in your vertical, who runs your process day to day and how they protect confidentiality. Our list of questions to ask an M&A advisor is a good starting point.
None of these is fatal on its own. Together they explain most of the gap between what a business could sell for and what it does.
Ready to Sell Your Online Business? Start With a Free Valuation
If you are thinking about how to sell an online business in 2026, the first step costs nothing and commits you to nothing. Get a free valuation from FE International and we will tell you what your business is worth based on comparable transactions, which route fits your price band, and what to fix before going to market. The conversation is confidential, the number is grounded in more than 1,500 completed deals, and the advice is the same whether you decide to sell this year, prepare for next year or keep building. You can also browse our market reports for the latest vertical-specific data. Every founder deserves to know what they have built is worth. Find out, then decide.